Beginner's Guide to Reading a Company Annual Report as a Citizen, Not an Investor
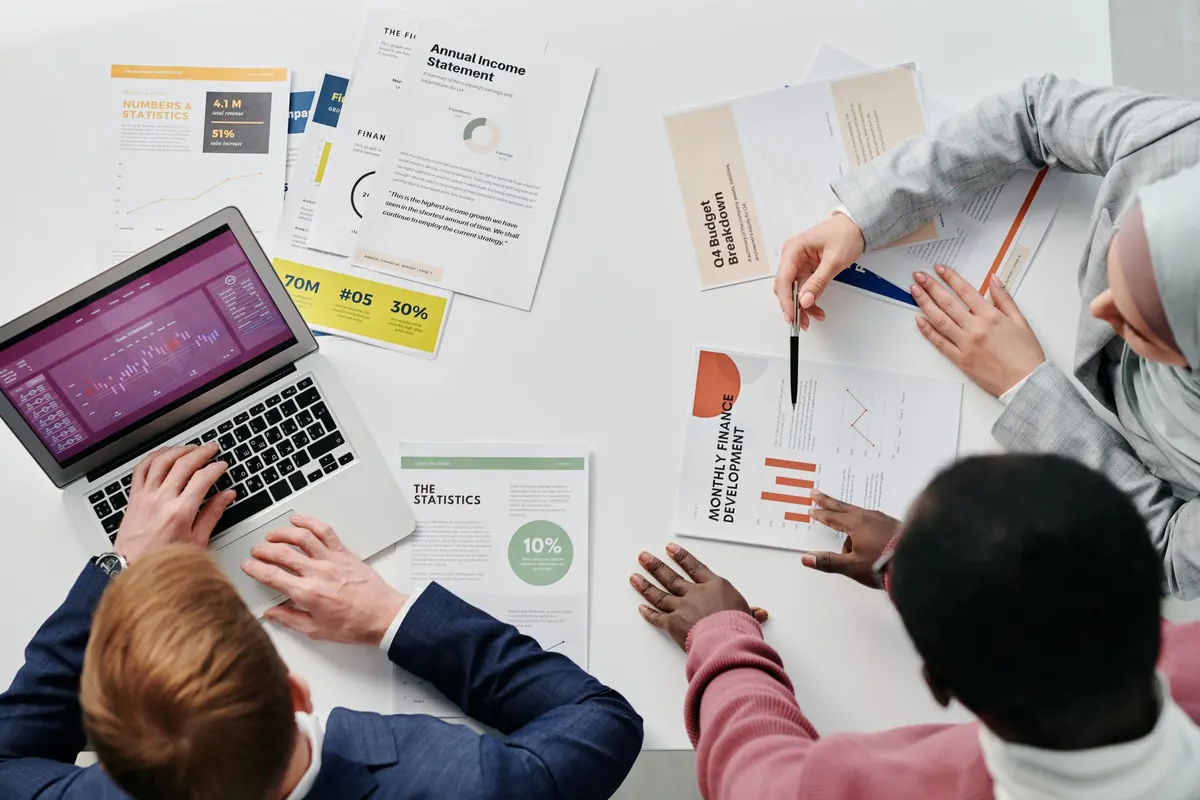
A company annual report is not written for you. It is written for shareholders, lenders and regulators, and it is drafted by people paid to make it read smoothly. That does not make it useless to everyone else. If you pay tax, work for a business, live near one, or buy its products, the report is one of the few places where a company has to put something on the record. You just need to know which bits are worth your time.
Most reports come in two halves that behave very differently. The front half is the polished part: chair's statement, strategy, market review, sustainability claims, board biographies, pay. The back half is the audited part: financial statements, the notes, and the auditor's report.
The single most useful habit is to treat the front half as an argument and the back half as the evidence. The auditor's opinion tells you whether the numbers give a true and fair view. Read it, then read the section on key audit matters, if there is one. That is where the auditor sets out the areas they found most judgemental. It is often the most honest page in the document.
Language shifts before numbers do. If last year's report led with volumes sold and this year's leads with "adjusted" profit, ask what changed. If a metric that appeared for three years quietly disappears, that is information too.
Watch for claims with no figure attached: "market-leading", "world-class", "significant progress". None of those can be checked. Targets are better, because they can be. Most reports restate the goals set two or three years ago. Sometimes those goals have moved, and the reason given for the move is more revealing than the goal itself.
Get comfortable with adjusted figures. They are legitimate and often useful, but the company defines them. Find the reconciliation to the statutory numbers in the notes. The gap tells you what is being excluded, and whether the exclusion is a one-off or a habit.
Profit involves judgement; cash is harder to argue with. Compare cash generated from operations with operating profit across several years. If profit rises steadily and cash does not, turn to the working capital note and find out why. Money tied up in stock or unpaid invoices is still a story about the business, even if the profit line looks healthy.
Look at borrowings, lease liabilities, pension obligations and goodwill. Goodwill is what remains when a company pays more for an acquisition than the assets were worth. Ask how much of it is attached to businesses that are now struggling, and whether it has been written down.
The notes are boring and frequently where the interesting things live: accounting policies, related party transactions, contingent liabilities, and the going concern statement.
Risk sections are often padded with generic warnings about economic conditions and currency movements. The value is in what is specific, quantified or new. Compare this year's list with last year's. A risk added is a signal. A risk removed shortly before it materialises is a question worth asking.
Two note headings repay attention:
The tax note shows current tax, deferred tax, and the difference between the effective tax rate and the headline rate. A gap is not automatically wrongdoing. It can come from operating in several countries, from timing differences, from reliefs such as research and development, or from prior-year adjustments. What matters is whether the report explains the main reconciling items, and whether the explanation is specific or vague.
Look for the company's published tax strategy if it has one, and for how tax is described in the risk factors — an unusually defensive tone is itself a signal. Large groups operating across borders face growing expectations of transparency, and some publish country-by-country information voluntarily. Where a company says little, the silence is a fair thing to note, though not a conclusion. For anything affecting your own tax position, speak to a qualified adviser.
Listed companies publish a remuneration report, and it is more readable than most people assume. Start with the single total figure for the chief executive, then break it apart: salary, annual bonus, long-term share awards, pension contributions. The interesting question is not how much, but what it was paid for.
Check the targets. Were they stretching when set, or comfortably beaten? Was the payout triggered by a measure that flatters performance, such as earnings before several inconvenient items? Are share awards subject to performance conditions or handed over regardless? Is there any sign of clawback being used? Some reports also disclose the ratio of chief executive pay to median employee pay, which puts the number in context.
You do not need to read 200 pages. An hour, in this order, gets you most of the way:
That last step matters. Read the persuasive pages after the factual ones, and you will notice the joins: the claim that does not match the cash, the cheerful sentence covering a difficult note.
You will not catch everything, and you are not meant to. Read one report a year for a company you care about — an employer, a local presence, a big supplier in your town — and you build a picture over time. Read it as a citizen rather than an investor, asking what the company does, what it says about itself, and where the two diverge. The questions come easily once you stop treating the document as marketing.
Photo: Tiger Lily / Pexels
Previous Post
How to Run a Local Campaign for a Safer High Street: A Step-by-Step Guide
Next Post
Seasonal Angle: How to Host a Debate Night for Friends Without Ruining Christmas Dinner